Interest on a credit card purchase is avoidable. It applies only when you carry a balance past the due date. Pay the statement balance in full and on time and no purchase interest is charged on those purchases.
The grace period is the window between the statement closing date and the payment due date, commonly about three weeks. For example, a statement that closes on the 1st and is due on the 22nd gives you about three weeks to pay. It generally applies only if you paid the previous statement in full. Carry a balance once and the grace period on new purchases can disappear, so fresh spending starts accruing interest from the day it posts.
The statement balance and the current balance are different figures. The statement balance is what you owed when the cycle closed. The current balance includes purchases made since that date. Paying the statement balance clears the interest-bearing amount even if newer purchases have posted, which is why paying the full current balance is not required to avoid interest.
Cash advances often behave differently. Interest may begin the day you take the money out, with no grace period, and issuers often charge a higher rate on cash than on purchases. Treat the grace period as a feature of purchases, not of every transaction on the card.
The APR is an annualized figure that combines the stated interest rate with eligible lender fees. Divide it by 365 to get the daily periodic rate, the rate applied to the balance each day.
Many issuers calculate interest on the average daily balance. Add each day's balance across the billing cycle and divide by the number of days in the cycle. The daily rate then applies to that average, producing the finance charge for the cycle.
A worked example makes the arithmetic concrete. Carry $2,000 for the first 15 days of a 30-day cycle and $3,000 for the next 15 days, and the average daily balance is $2,500. At a 25% APR the cycle interest is roughly ($2,500 × 0.25 ÷ 365) × 30, about $51. Pay $500 on day 10 instead of day 30 and the schedule changes: $2,000 for days 1 through 9, $1,500 for days 10 through 15, and $2,500 for days 16 through 30. That average daily balance is about $2,150, and the finance charge falls to roughly $44. The payment lowers the balance across the final 21 days of the cycle, so more days carry a smaller amount, which pulls the average down.
Rates are not fixed. Commonly cited purchase APRs sit near 25% to 28%, with cash advance rates often higher. They vary by issuer, region, and card type, and they move with market conditions, so treat any single figure as illustrative.
Interest left unpaid at the due date is added to your balance, and that added interest can itself accrue interest in the next cycle. That is compounding, and it is why a card balance can grow even while you keep paying on time.
Minimum payments are applied to interest and fees first. Only what remains reduces principal, so progress is slow while the balance stays high. Consumer guidance illustrates the scale: a $5,000 balance at 25% APR with a $50 monthly minimum can take about 175 months, roughly 14.5 years, and about $13,500 in total payments. The example assumes no new purchases and an unchanged rate, so treat it as an illustration, not a forecast. Paying an extra $50 each month would reduce the principal faster and cut the total interest, though the exact savings depend on the rate and the remaining term.
New spending compounds the problem. Interest is charged on new purchases until the balance is settled in full, so a card that is already revolving turns routine spending into a longer payoff. A $1,000 balance at 25% APR accrues about $0.68 in interest per day, which is added to the balance and can accrue interest itself.
Missing the minimum, or paying less than it, can trigger a late fee and additional finance charges, and those amounts attract interest too. Repeated misses can lead to suspended credit lines and can damage your credit scores, which raises the cost of other borrowing.
Four rules cover most of the ground.
- Pay the statement balance in full before the due date. Nothing else reliably eliminates purchase interest.
- If you already carry a balance, pay more than the minimum and direct the extra dollars at the highest-APR balance first. Each extra dollar reduces both the principal and the interest the next cycle charges.
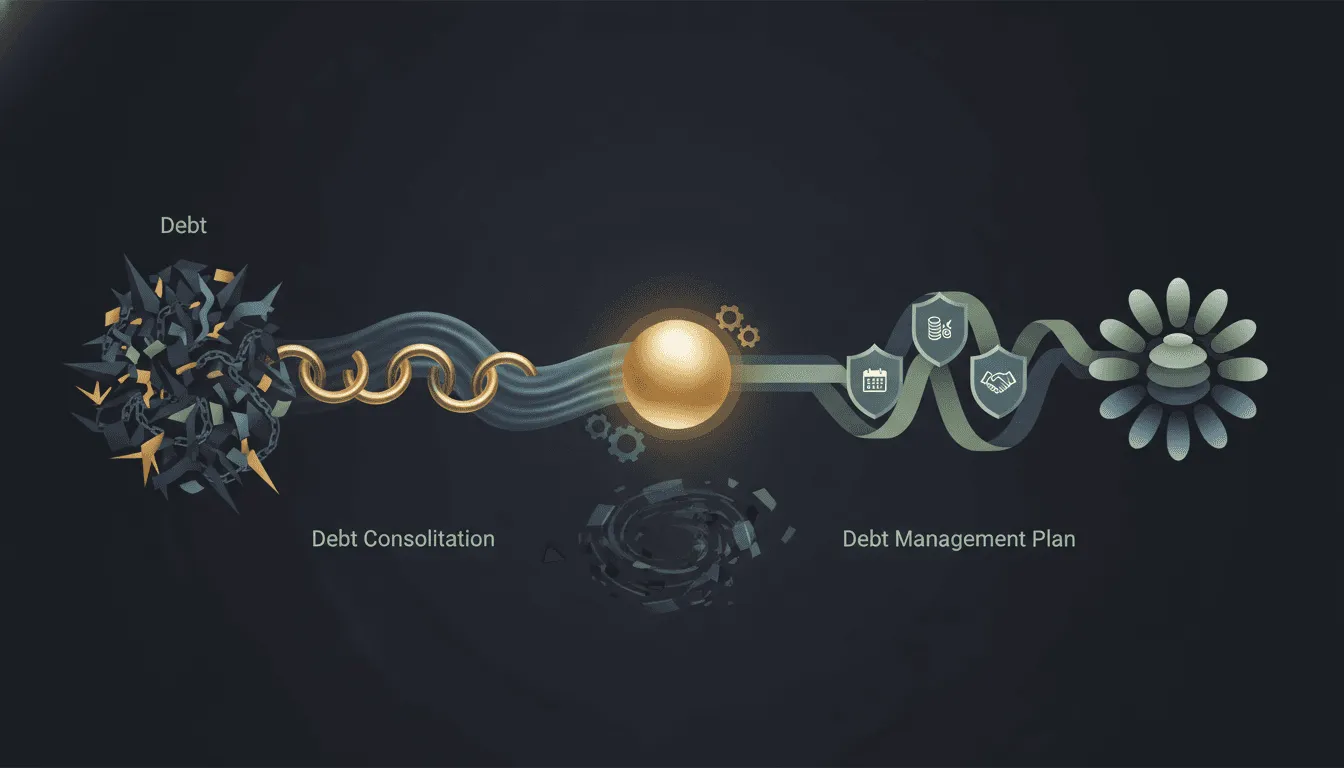
- A 0% intro APR or a balance transfer buys time but does not erase the debt. Balance transfers commonly carry a fee, and the promotional rate ends on a set date. Check the fee, the promotional period, and whether the offer covers new purchases or only the transferred balance, then aim to clear the amount before the promotion ends. Whatever remains accrues interest at the standard rate.
- A charge card requires full payment each cycle. By removing the option to revolve, it acts as a structural guardrail if you know you tend to carry a balance.
A consistent payment habit makes these rules easier to keep. Schedule the payment a few days before the due date; a payment that arrives late loses the grace period. Keeping a small cash buffer, even an emergency fund built slowly, reduces the chance that an unexpected bill forces new spending onto the card.
This is general education, not individual financial advice. Terms, fees, and rates vary by issuer and location, so check your card agreement for the figures that apply to you.