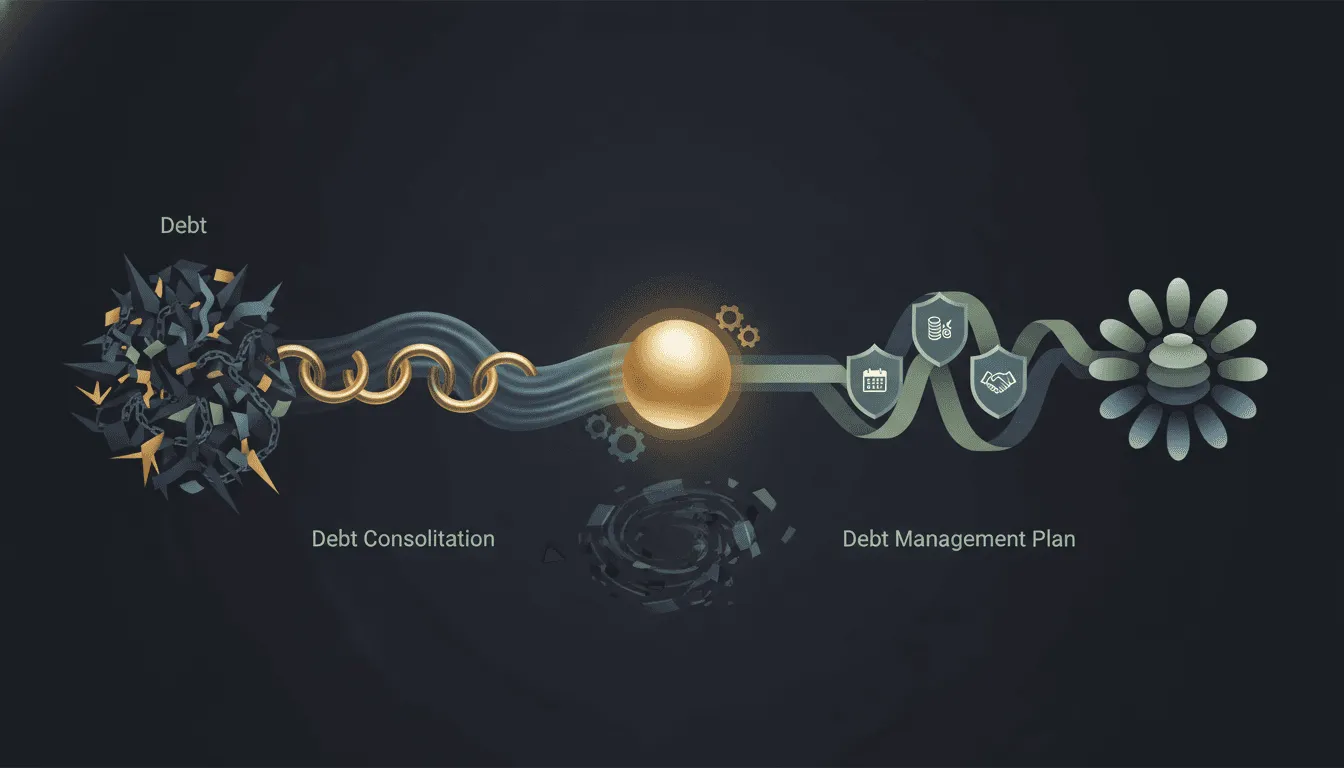
Debt consolidation replaces several debts with one new obligation. A consolidation loan pays off your existing balances and leaves you with a single fixed monthly payment to one lender. A balance transfer credit card does the same from the other direction: you move existing balances onto a new card, ideally one carrying a 0% introductory APR on transfers, and repay that card instead of the original creditors.
The process runs in three stages. You apply, and the lender runs a credit check. If the loan or transfer is approved, the funds settle the old accounts. You then repay the new debt on its own schedule. Lenders may close the cleared accounts or leave them open. Leaving them open helps only if you keep them at a zero balance, since running them up again restores the debt you just retired.
The appeal is a lower rate. One illustration from SingSaver: consolidating $9,000 of debt at a 25% effective interest rate into a loan at a 17% EIR repaid over two years could save about $820 in interest. The saving comes from the gap between the two rates applied across the full term, not from consolidating as such. Your own figure depends on the rate you qualify for, any origination or transfer fee, and regional market conditions.
Consolidation is not automatically cheaper. If your credit keeps you out of a lower rate, the new loan can cost more than the debts it replaces. A 0% balance transfer carries a deadline as well: clear the full balance before the promotional period ends, or the remainder starts accruing interest at the card's standard rate.
A debt management plan is a repayment arrangement built by a credit counseling agency, not by a lender. The counselor reviews your income, outgoings, and debts, then approaches your creditors to ask for concessions: lower interest rates, waived fees, or a halt to further charges. You make one monthly payment to the agency, which disburses the agreed amounts to each creditor. MoneySmart and StepChange both describe this structure.
Creditors are not obliged to accept the terms the agency proposes, so a plan can cover some accounts and leave others out. Because the agency holds and forwards your payment, missing it delays every creditor in the plan at once. Enrollment usually requires you to stop using credit, and agencies often ask you to close or freeze existing accounts so the balances cannot grow again. You work to a budget for the life of the plan.
Concessions change the arithmetic of repayment. A lower interest rate sends a larger share of each fixed payment to principal, so the balance falls faster. A halt to further charges stops late fees and penalty interest from adding to what you owe. A waived fee removes a one-off cost. The agency's leverage is the promise of steady payments; a creditor weighs that against the cost of collection.
Credit reporting during a DMP varies by creditor and bureau. Experian notes that debt management plans may have different credit impacts but does not specify how each creditor reports or whether the plan appears on your file.
Cost is usually a monthly service fee. Many agencies are nonprofits that waive or reduce fees for borrowers on low incomes; others operate for profit. Ask for a written fee schedule before enrolling, and check which category the agency falls into. Pairing a plan with a structured budget helps if your goal is rebuilding the habits underneath the debt.
Negotiation is the structural difference. Consolidation involves none: the lender pays each creditor in full and the relationship ends there. A DMP exists because the agency bargains on your behalf. When a creditor refuses the proposed terms, that account stays on its original schedule and sits outside the plan, so one DMP can run on two sets of terms at once. You then pay the agency for the enrolled accounts and pay any excluded creditor directly on that creditor's original terms.
Credit impact follows that split. A consolidation loan or transfer card adds a new account and a hard inquiry at application, either of which can dip your score temporarily; on-time payments then build positive history. A DMP adds no new borrowing, but creditors may report the plan. Missed payments from before you enrolled typically weigh more than the plan entry does.
Singapore draws the line the same way. A Debt Consolidation Plan merges unsecured debts into a single loan with one monthly instalment, while a Debt Management Plan coordinates managed repayments, often through an approved agency. A separate Debt Repayment Scheme exists for some insolvency cases.
Choosing between them comes down to your credit, your cash flow, and whether you will change the spending that created the balances. If your credit qualifies you for a lower-rate loan or a 0% transfer offer, and you will clear the balance before the promotional period ends, consolidation usually costs less. If your credit is fair or poor, minimum payments are overwhelming you, and you need creditors to cut rates or fees, a DMP fits better.
If you cannot afford even the reduced payments a DMP would set, free debt advice can lay out alternatives such as debt relief orders, individual voluntary arrangements, or bankruptcy. Each has its own eligibility criteria and consequences.
A credit score check gives you the number that decides which option you can even access.
This is general education, not individual financial advice. A nonprofit credit counselor or financial adviser can assess your situation.